
Southern Copper (SCCO): Strong Numbers, Unanimous Sell Rating
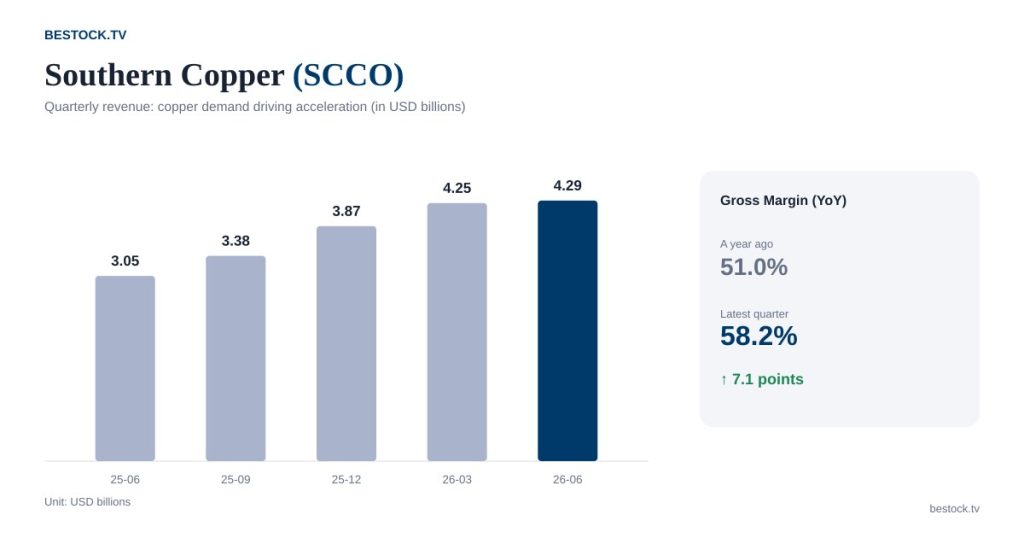
I’m covering Southern Copper here as a global growth and electrification trade, not as a mining stock pick in isolation, because copper demand is one of the cleanest proxies I know for whether the market believes the grid build-out, EV adoption, and data center expansion story is actually translating into physical commodity demand. And right now there’s a real split: the operating numbers say the demand story is strong, while the analyst panel covering this stock is unanimously negative.
The Numbers Say Copper Demand Is Running Hot
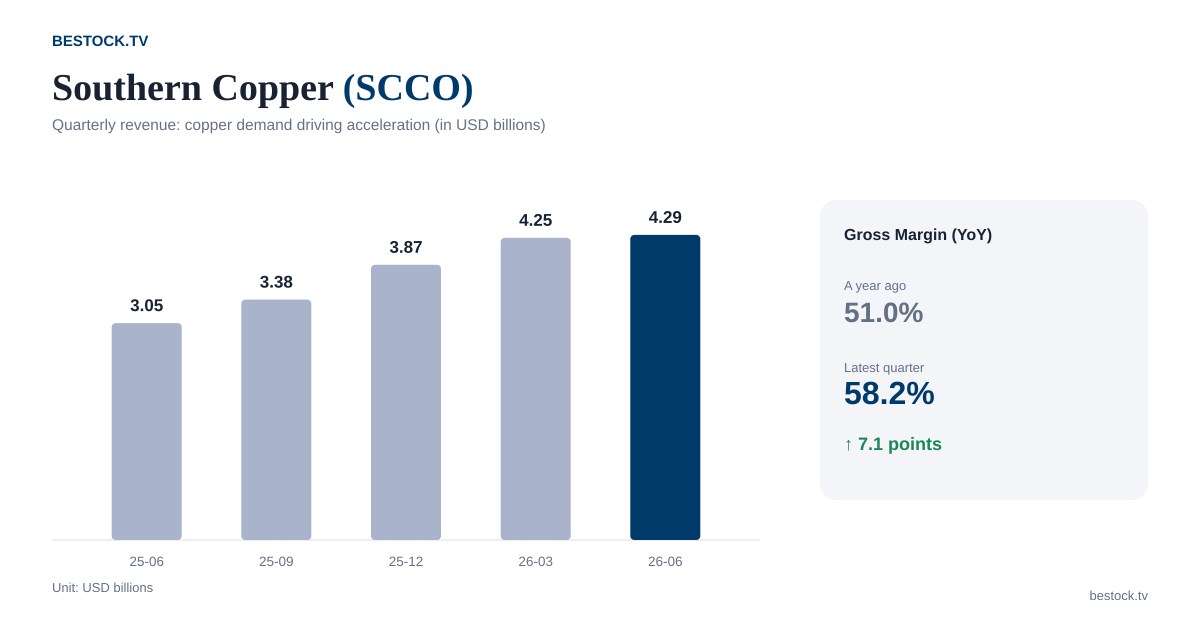
Revenue: $3.05 billion, $3.38 billion, $3.87 billion, $4.25 billion, $4.29 billion, with year-over-year growth accelerating from negative 2.2% up to 40.6% across those five quarters. Gross margin climbed right alongside it, from 51.0% a year ago to 58.2% now, a 7.1-point jump that tells me this isn’t just a volume story, pricing power is doing real work here too. Net income is up 71.6% year over year in the latest quarter. On every operating metric I track, this is one of the stronger acceleration stories in this entire series.
And Yet the Analyst Panel Says Sell
Six analysts cover this stock. Zero rate it a Buy. The consensus rating is Sell, with an average price target of $159.65, nearly 20% below where the stock is trading today. I want to be direct about this rather than talk around it: I don’t fully understand the gap between numbers this strong and a sell-side consensus this negative, and I think the most likely explanation is that analysts are pricing in a copper price correction from currently elevated levels that hasn’t shown up in the trailing financials yet, since commodity-linked earnings can look fantastic right up until the price cycle turns.
The Valuation Sits in the Middle, Which Doesn’t Resolve the Disagreement
Current P/E (TTM) is 29.0, against a historical average of 23.7, putting the stock at the 74.8th percentile of its own history, moderately rich but not extreme. That valuation alone doesn’t explain a unanimous Sell rating from six analysts who presumably have access to the same commodity price forecasts I don’t have in front of me.
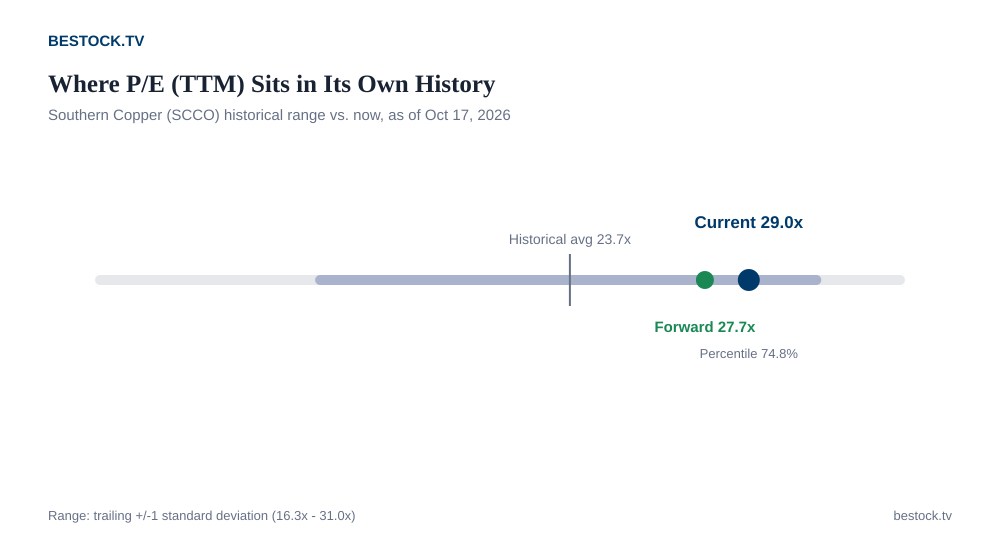
Table: The Numbers Side by Side
| Metric | Value | Context |
|---|---|---|
| Share price | $198.04 | 52-week range $113.90 to $220.78 |
| P/E (TTM) | 29.0 | 74.8th percentile |
| P/E (forward) | 27.7 | close to TTM |
| Dividend yield | 1.82% | |
| Market cap | $167.2 billion | |
| Analyst rating | 6 analysts, 0% Buy (Sell consensus) | unanimous, small sample |
| Average price target | $159.65 | about 19% below the current price |
Why I’m Not Simply Deferring to the Analysts Here
Six analysts is a thin sample, and commodity-stock coverage tends to be more backward-looking on price-cycle calls than the operating data I’m seeing right now suggests is warranted. I’m not dismissing their view, a correction in copper prices is a real and recurring risk in this sector, but I think the acceleration in volume and margin I’m seeing is at least partial evidence of genuine demand growth from electrification and AI-related infrastructure build-out, not just a price spike that’s about to reverse.
What I’m Doing, and the Number I’m Watching
I own a small position here specifically as a macro hedge on the electrification and grid-buildout theme, sized small because I take the unanimous Sell rating as a real signal of risk I don’t have full visibility into. The number I’m watching is gross margin: continued expansion past 58% would support my read that this is demand-driven rather than a peaking price cycle, while a reversal back toward 52-53% would tell me the analysts calling Sell were ahead of the data, not behind it.
Analysis and opinion only, not investment advice. Figures come from the company’s recent filings and our market data snapshot; the valuation percentile comparison is my own calculation.