
NextEra Energy (NEE): A Rate Trade Dressed Up as a Utility Stock
NextEra Energy is a utility, but I’m covering it here as a rates trade, because that’s what it actually is underneath the regulated-business label. Renewable energy projects are financed with enormous amounts of debt against long-dated contracted cash flows, which makes a stock like this one of the more direct equity proxies for where the market thinks interest rates are headed over the next few years.
The Operating Numbers Are Already Telling the Rate Story
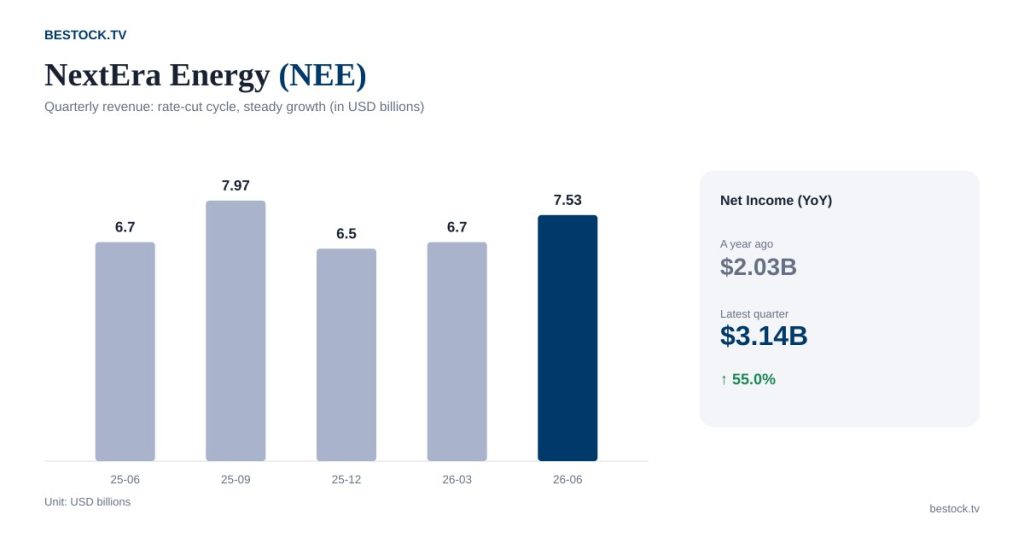
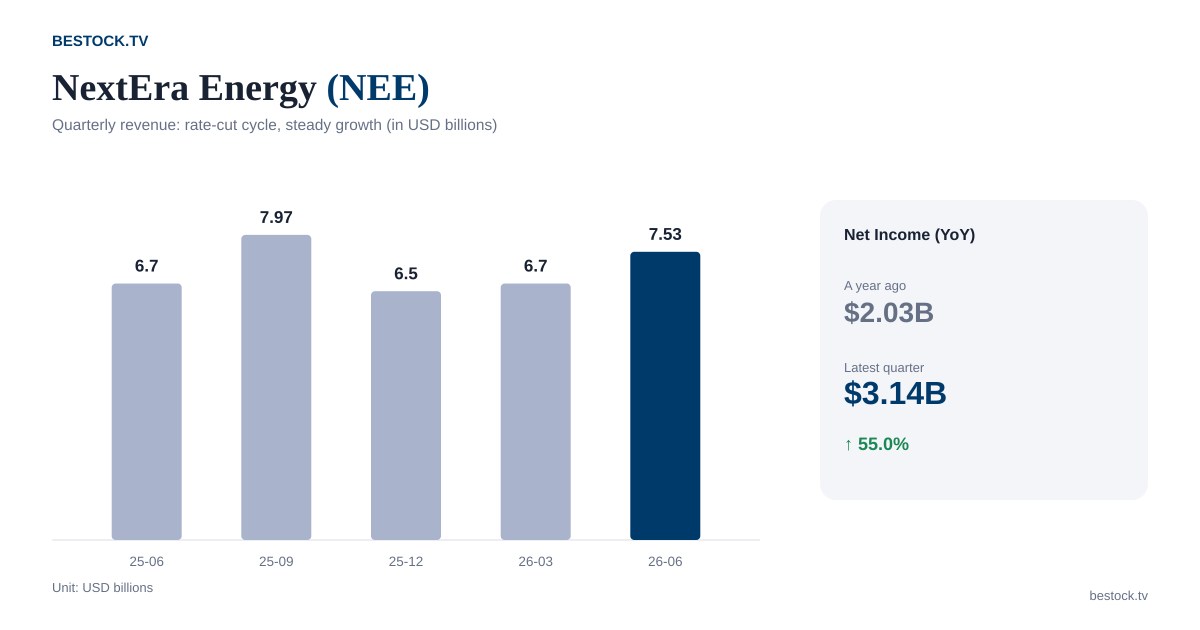
Revenue: $6.70 billion, $7.97 billion, $6.50 billion, $6.70 billion, $7.53 billion, growing a healthy 12.4% year over year in the latest quarter. Net income jumped to $3.14 billion from $2.03 billion a year earlier, up 55.0%. That’s a strong number on its face, and part of what’s driving it is lower financing costs on the variable and recently-refinanced portions of NextEra’s debt load as rate expectations have eased from where they were a year ago. A utility holding company reporting a 55% profit jump isn’t something you see without either a rate tailwind or an unusual one-time item, and here I think it’s genuinely the former.
The Valuation Hasn’t Fully Caught Up to the Earnings Trend
Current P/E (TTM) is 17.9, against a historical average of 33.7 and a trailing band of 11.7 to 55.6, putting the stock at just the 15.9th percentile of its own history, cheap by its own standards. For a business whose profit growth is being helped by the rate environment rather than hurt by it right now, a multiple this far below its historical average suggests the market hasn’t fully updated its view on NextEra specifically, even if it’s updated its view on rates generally.
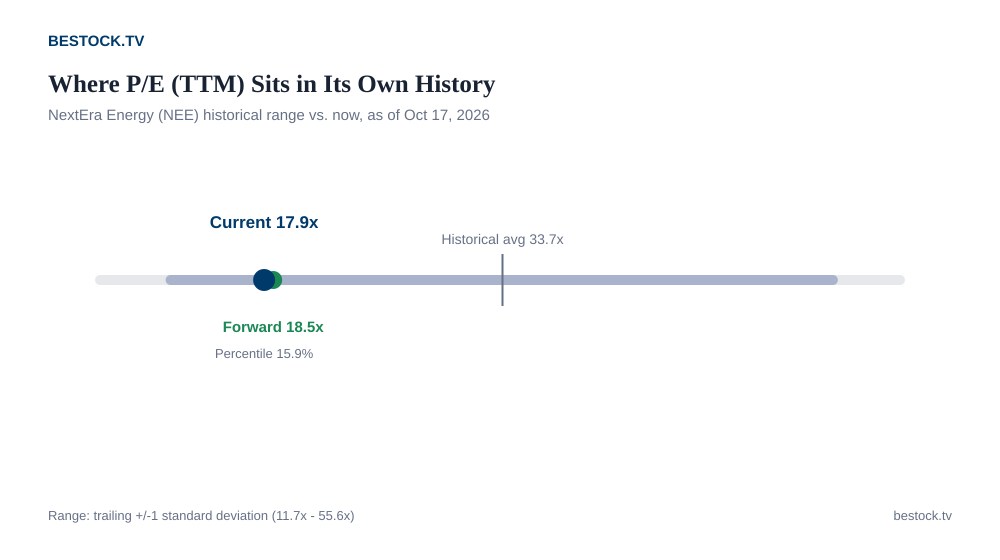
Table: The Rate-Trade Numbers
| Metric | Value | Context |
|---|---|---|
| Share price | $78.95 | 52-week range $74.41 to $97.30 |
| P/E (TTM) | 17.9 | 15.9th percentile, historically cheap |
| P/E (forward) | 18.5 | roughly in line with TTM |
| Dividend yield | 3.01% | |
| Market cap | $164.7 billion | |
| Analyst rating | 12 analysts, 58% Buy | |
| Average price target | $96.55 | about 22% above the current price |
A 22% implied upside combined with a 15.9th percentile valuation is a larger gap than I usually see on a company this size, which tells me this is less a stock-picking call than a macro one: the trade is “rates stay stable to lower,” expressed through a well-run renewable utility rather than through a bond fund or a rate-sensitive ETF.
Where I’d Be Early and Wrong
If inflation proves stickier than expected and long rates climb back up over the next few quarters, NextEra’s financing costs would rise again and this quarter’s 55% profit jump would look like a temporary window rather than a new trend. I’d rather make this call now, while the valuation still reflects skepticism, than wait for consensus to catch up and pay a higher price for the same thesis. That’s a deliberate choice to be early, and early calls on rates are wrong often enough that I want to be upfront about the risk.
What I’m Doing, and the Number I’m Watching
I’m building a position gradually rather than all at once, specifically because this is a rate call dressed up as a utility stock, and rate calls deserve smaller position sizing than a pure business-fundamentals thesis. The number I’m watching isn’t anything in NextEra’s own filings, it’s the 10-year Treasury yield: a continued drift lower is what would validate both this stock’s cheap valuation and the profit trend behind it.
Analysis and opinion only, not investment advice. Figures come from the company’s recent filings and our market data snapshot; the valuation percentile comparison is my own calculation.